
Learn how craft spirit companies can improve cash flow with invoice factoring and specialty financing while waiting for distributors and commercial customers to pay.

Cash flow is one of the most important financial concerns for craft spirit companies, especially importers and growing brands selling through distributors, retailers, restaurants, bars, and other commercial customers. A business can have strong sales, healthy margins, and growing demand, yet still experience cash shortages simply because customers have not paid their invoices.
This challenge is particularly common in the craft spirits industry. Companies often need to pay suppliers, freight providers, warehouses, customs-related expenses, taxes, employees, marketing costs, and other operating expenses before they receive payment from their customers. When invoices are subject to payment terms such as Net 30, Net 60, or longer, a significant amount of working capital can become tied up in accounts receivable.
For many craft spirit companies, the traditional response to a cash-flow shortage is to approach a bank for a business loan or line of credit. However, traditional bank financing is not always the right fit for a company whose biggest financial asset is its outstanding customer invoices. Bank loans can involve lengthy approval processes, strict qualification requirements, collateral requirements, financial covenants, and additional debt on the company’s balance sheet.
Alternative financing strategies can provide another way to manage this gap. Invoice factoring and specialty financing can help qualified businesses access working capital based on their existing business activity and receivables rather than relying solely on traditional borrowing.
For craft spirit companies, this can create greater flexibility when cash is needed to support inventory, fulfill new orders, manage growth, or keep operations moving while waiting for distributors and commercial customers to pay.
The craft spirits business has a cash-flow cycle that can be quite different from a typical service business. Companies may need to invest significant amounts of money long before they receive revenue from a completed sale.
For an importer, the process can begin months before a product reaches a US customer. The company may place an order with a producer, arrange transportation, handle import requirements, pay applicable duties and taxes, move products into a warehouse, and prepare inventory for distribution. After the product is sold to a distributor or commercial customer, the importer may still have to wait weeks or months before receiving payment.
This creates a timing problem.
A company may have $250,000 in outstanding invoices and still have difficulty paying a $50,000 expense that is due this week. The problem is not necessarily profitable. The problem is that the company’s cash is sitting in accounts receivable.
As the company grows, this issue can become more significant. Higher sales can produce higher accounts with receivable balances. If customers are paying more slowly while the business is simultaneously purchasing more inventory, the company may experience increasing working-capital pressure even while revenue is growing.
This is why cash-flow management should be considered separately from profitability.
A profitable company can run into a cash shortage. Likewise, a company can have substantial assets and future sales opportunities but still need immediate working capital to meet current obligations.
One of the most important concepts for growing craft spirit companies is understanding that revenue does not automatically equal available cash.
Suppose an importer sells $100,000 of products to a distributor on Net 60 terms. The company can record the sale according to the applicable accounting rules, but the $100,000 has not necessarily arrived in its bank account.
During those 60 days (about 2 months), the business may need to pay suppliers, warehouse fees, transportation expenses, payroll, insurance, marketing costs, taxes, and other bills.
The company therefore has a working-capital gap between the time it makes a sale and the time it collects the money.
The larger the business becomes, the more important this gap can become. A company with $1 million in annual sales may be able to manage receivables easily. A company rapidly moving toward $5 million, $10 million, or more in sales may need significantly more working capital simply because more money is continuously tied up in unpaid invoices.
Managing this gap effectively can allow a company to pursue growth without unnecessarily taking on conventional bank debt.
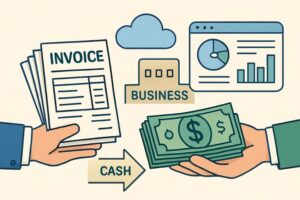
Invoice factoring is one financing approach that can help businesses convert qualifying outstanding invoices into working capital.
Instead of waiting for a distributor or commercial customer to pay an invoice according to its normal payment terms, a business can work with a factoring company to access a portion of the invoice value earlier.
The basic concept is straightforward.
A craft spirit company completes a sale and issues an invoice to an eligible customer. Rather than waiting until the invoice reaches its due date, the company can factor in the receivable with a financing provider. The provider advances funds against the qualifying invoice, giving the business access to cash sooner. When the customer pays the invoice, the transaction is settled according to the factoring agreement and applicable fees.
The exact advance amount, fees, eligibility requirements, customer requirements, and structure depend on the financing provider and transaction.
The key benefit is timing. Invoice factoring can turn an otherwise delayed cash inflow into working capital that can be used today.
For a craft spirit importer, that additional liquidity can be particularly useful because the company may need to purchase the next shipment, pay warehouse expenses, support sales efforts, or take advantage of a new distribution opportunity before its previous invoices have been collected.
One of the reasons invoice factorings can be relevant to craft spirit companies is that accounts receivable can represent a substantial business asset.
A company may have already done the work of selling its products. The customer may have accepted the goods and received an invoice. The remaining issue is simply the payment period.
Factoring provides a mechanism for accessing cash associated with those receivables before the customer pays under normal terms.
Consider a simplified example.
A craft spirit importer sells $200,000 of inventory to a distributor with Net 60 payment terms. The importer now has $200,000 in accounts receivable, but the cash may not arrive for approximately two months.
During that period, the importer identifies another opportunity to purchase inventory from its producer. Without additional liquidity, the company may have to delay the purchase, negotiate extended supplier terms, use existing cash reserves, or seek another source of financing.
With an appropriate factoring arrangement, the company may be able to access a portion of the qualifying $200,000 receivable earlier. This can provide working capital while the distributor continues through its normal payment cycle.
The result is not necessarily an increase in sales. Instead, financing can improve the timing between sales and cash collection.
That distinction is important.
Traditional bank debt and invoice factoring can serve different purposes.
A bank loan involves borrowing a specified amount of money and repaying principal and interest according to an agreed schedule. Depending on the facility, the bank may evaluate the company’s financial history, profitability, credit profile, collateral, cash flow, and other factors.
Invoice factoring is structured around qualifying accounts receivable. Rather than simply borrowing against an unrelated asset, the financing is connected to invoices generated from actual commercial sales.
This distinction can be useful for growing craft spirit companies whose sales are increasing but whose cash flow has not yet caught up with that growth.
For example, a newer importer may have strong purchase orders and growing distributor relationships but may not have the lengthy operating history or conventional collateral that a traditional lender wants to see. Its accounts receivable, however, may provide a financing opportunity.
Factoring allows financing capacity to grow with eligible receivables. The actual availability depends on the factoring provider, the quality of the receivables, customer creditworthiness, transaction structure, and other underwriting considerations.
Invoice factoring is only one part of the broader specialty financing landscape.
Craft spirit companies often have financial requirements that do not fit neatly into a standard lending model. Their cash flow can be influenced by inventory purchases, production schedules, international shipping, distributor relationships, seasonal demand, import costs, and the timing of customer payments.
Specialty financing measures where a more customized approach may be appropriate.
Rather than if every company should use the same financing product, specialty financing can consider the specific circumstances of the business. The objective is to identify a financing structure that aligns with the company’s actual working capital requirements.
For craft spirit importers, this may be especially important when the business needs capital for inventory and operations while waiting for receivables to convert into cash.
The right financing structure can help management focus on operating the company rather than constantly managing short-term cash shortages.
Inventory is often one of the largest uses of cash for a craft spirit importer.
A company may have an opportunity to bring in a new tequila, Scotch whisky, mezcal, rum, gin, or other specialty spirit. However, purchasing inventory requires capital before the company can generate revenue from that inventory.
If too much cash is tied up in outstanding invoices, the company may have difficulty funding the next purchase.
This creates a cycle where sales growth increases financial pressure.
Access to working capital can help break that cycle. When a company can access cash associated with eligible receivables, it may have more flexibility to purchase inventory and respond to customer demand without waiting for every previous invoice to be paid.
For growing brands, this can be particularly valuable when demand is unpredictable. A distributor may suddenly request a larger shipment; a retailer may expand its order, or a successful promotion may increase product movement.
The company needs to have sufficient inventory and working capital to respond.
Distributor relationships are critical to craft spirit companies, but payment terms can create working potential challenges.
A distributor may have established payment procedures that require the supplier to wait a certain period after delivery or invoicing. These terms may be commercially normal, but they can still create pressure on the supplier.
For example, a craft spirit company might have several distributors purchasing products throughout the month. Each distributor could have different payment schedules, credit profiles, and order volumes.
This means the company’s accounts’ receivable balance can become complex.
Invoice factoring can accelerate cash from qualifying invoices rather than requiring the company to wait for every distributor’s standard payment cycle.
This can help management make more predictable decisions about purchasing, payroll, marketing, and other operating expenses.
Growth is often viewed as an entirely positive development, but rapid growth can create financial stress when working capital is not managed properly.
Imagine a craft spirit importer that doubles its sales over a relatively short period. Revenue increases, but so do inventory requirements, shipping expenses, warehouse needs, accounts receivable, and other operating costs.
If customers take 30 to 60 days (about 2 months) to pay, the company may need to finance a larger working-capital gap than it did when sales were smaller.
This is called the growth paradox: the business is doing more but has less cash.
Specialty financing can provide a mechanism for managing this growth period. By accessing working capital tied to qualifying receivables, a company can potentially support increasing sales without automatically increasing its traditional bank debt.
The financing strategy should still be carefully evaluated. Companies need to understand the costs, terms, customer eligibility, advance rates, and settlement requirements before entering into an agreement.
Working capital is not only about paying bills.
It can also give a company the flexibility to act when opportunities appear.
A craft spirit importer might receive an opportunity to secure additional inventory from a producer. A distributor might want to expand its territory. A retailer might request a larger order. A company might want to participate in a major tasting event or increase its marketing activity before a key selling season.
If all available cash is tied up in accounts receivable, management may have to turn down or delay these opportunities.
Access to working capital can provide additional flexibility.
The company can use financing for business while waiting for customers to pay outstanding invoices. This can help separate the timing of cash collection from the timing of business decisions.
Another consideration for growing craft spirit companies is financing diversification.
Businesses do not necessarily need to rely on one source of capital for every situation. A company might use its operating cash for regular expenses, supplier terms for certain purchases, and receivables financing for customer invoices.
The goal is to match the financing method to the underlying business needs.
For example, long-term investments may require a different financing structure than short-term working-capital requirements. Equipment purchases may be different from financing a 60-day accounts receivable cycle.
Using the appropriate financial tool for the appropriate need can help management avoid using expensive or inflexible capital for purposes it was not designed to support.
Improving cash flow is also about making financial planning more predictable.
When management understands how much money is tied up in accounts receivable and when that money is expected to become available, it becomes easier to forecast future cash requirements.
Companies can monitor metrics such as accounts receivable aging, days sales outstanding, inventory turnover, gross margins, customer payment patterns, and projected cash inflows.
These measurements can help identify potential cash shortages before they become emergencies.
For craft spirit businesses, this type of visibility is particularly important because cash requirements can fluctuate throughout the year. Seasonal sales, promotional campaigns, inventory purchases, production schedules, and distributor ordering patterns can all affect working capital.
A financing partner that understands these dynamics can become part of a broader cash-flow strategy rather than simply providing money when a problem occurs.
Not every invoice will necessarily qualify for factoring.
The financing provider may consider factors such as the customer responsible for paying the invoice, the age of the receivable, payment history, documentation, disputes, and other transaction-specific criteria.
This makes accounts receivable management important.
Craft spirit companies should maintain accurate customer records, clear invoices, delivery documentation, purchase orders, and consistent payment records. Strong receivables management can make it easier to evaluate which invoices may be appropriate for financing.
Businesses should also understand the difference between financing a legitimate receivable and using financing to cover an underlying operational problem. Factoring can help manage timing, but it does not replace sound pricing, inventory management, expense control, or customer-credit practices.
The objective of specialty financing should not simply be to obtain cash as quickly as possible.
A stronger approach is to integrate financing into the company’s overall working capital strategy.
Management should understand how much capital is required to support current sales, how quickly customers pay, how much inventory must be maintained, and how much cash is required for upcoming purchases and operating expenses.
The company can then evaluate whether invoice factoring or another specialty financing solution fits those needs.
For some businesses, the primary issue may be slow-paying commercial customers. For others, inventory purchases may create the biggest cash requirement. Some businesses may need financing solutions as they move through different stages of growth.
The important point is that financing should be connected to the company’s actual cash flow cycle.
Craft spirit businesses operate in a specialized commercial environment. A financial partner working with these companies should understand that revenue growth, inventory, receivables, distributor relationships, and import-related expenses can all affect liquidity.
A financing provider that understands the industry can have a better appreciation for why a company may need working capital even when sales are increasing.
For craft spirit importers, this specialized perspective can be valuable when evaluating accounts receivable, distributor payment cycles, and other working-capital requirements.
TAG Financial Services positions invoice factoring as a way for businesses to access cash from outstanding invoices. For craft spirit companies, this approach can provide working capital while distributors and commercial customers continue through their normal payment terms.
Conclusion: Turn Outstanding Invoices into an Opportunity
Craft spirit companies do not necessarily need to rely exclusively on traditional bank debt to manage working-capital needs. When cash is tied up in outstanding invoices, invoice factoring can allow access to cash sooner and improve liquidity while customers complete their normal payment cycles.
Specialty financing can also give growing craft spirit businesses a more customized approach to working capital, helping them manage inventory purchases, distributor relationships, operating expenses, and growth opportunities.
For companies looking for financing solutions built around the realities of their business, TAG Financial Services offers a specialized approach to working capital. By helping businesses access cash from qualifying outstanding invoices through invoice factoring and providing specialty financing solutions, TAG can help craft spirit companies manage the gap between making a sale and receiving payment.
When growth is limited by the timing of cash—not the demand for your products—having the right financial partner can make a meaningful difference.
 0
"*" indicates required fields


